Wildfire Insurance in the Colorado Foothills: A Jeffco West Guide for Buyers and Owners
The short answer
Yes, insurance takes more planning on a Jeffco foothills home, but it's workable. Since October 1, 2026, Colorado admitted insurers and the FAIR Plan that use wildfire risk scores must tell you your score, explain it, and let you appeal with proof of mitigation. Start quotes early, ask your carrier which mitigation it credits, and keep records of the work.
Why I'm writing this
I help people buy, sell and renovate homes across Jeffco West, from Bailey to Golden. Lately insurance comes up before almost anything else — sometimes before the first showing. I'm not an insurance agent and this isn't insurance or legal advice. What I can do is point you to what the state actually says, so your conversation with your carrier goes better.
What changed in Colorado: HB25-1182
HB25-1182, "Risk Model Use in Property Insurance Policies," was signed May 28, 2025 and took effect July 1, 2026. According to the Colorado Division of Insurance (DOI), its consumer notices begin October 1, 2026. It applies to admitted insurers and the Colorado FAIR Plan. It does not apply to non-admitted or surplus lines insurers.
If an insurer uses a wildfire risk model or score to price, underwrite, surcharge or non-renew a policy, the DOI says it must:
- Give you a written wildfire risk notice. It must include your property's score or classification, a plain-language explanation of how it was calculated, the full range of possible scores, the property or area features that drove it, the impact mitigation has, and your right to appeal.
- Hit set timelines. New applicants get the score within 15 days of a completed application. Existing policyholders get it with the renewal offer, or with a nonrenewal notice.
- Handle appeals. If you appeal with evidence of mitigation, the insurer must acknowledge it within 10 calendar days and give a written decision within 30 calendar days. If the decision runs past your policy's expiration, coverage must continue at least 10 calendar days after you're notified.
- Count mitigation. Insurers must build property-level and community-level mitigation into their models, or give a discount to policyholders who show qualified mitigation work.
- Publish it. Insurers must post their mitigation discounts and appeal process on their websites — or post that discounts aren't available.
The DOI points to verified programs, such as those from the Insurance Institute for Business and Home Safety (IBHS), as examples of qualified mitigation, and encourages homeowners to ask their insurer which standards it recognizes.
Quick reference table
Topic | What the source says | Source |
|---|---|---|
Law | HB25-1182, signed May 28, 2025; effective July 1, 2026 | Colorado General Assembly |
Wildfire risk notices | Begin Oct 1, 2026 — at application or at renewal | Colorado DOI |
Who it covers | Admitted insurers and the Colorado FAIR Plan; not surplus lines | Colorado DOI |
Score for new applicants | Within 15 days of a completed application | Colorado DOI |
Appeal acknowledgment | Within 10 calendar days | Colorado DOI |
Appeal decision | Within 30 calendar days | Colorado DOI |
FAIR Plan eligibility | Proof of 3 declinations; apply through a licensed agent | Colorado FAIR Plan; C.R.S. 10-4-1808 |
FAIR Plan homeowner limit | Up to $750,000 property + contents, actual cash value | Colorado Division of Real Estate; C.R.S. 10-4-1807 |
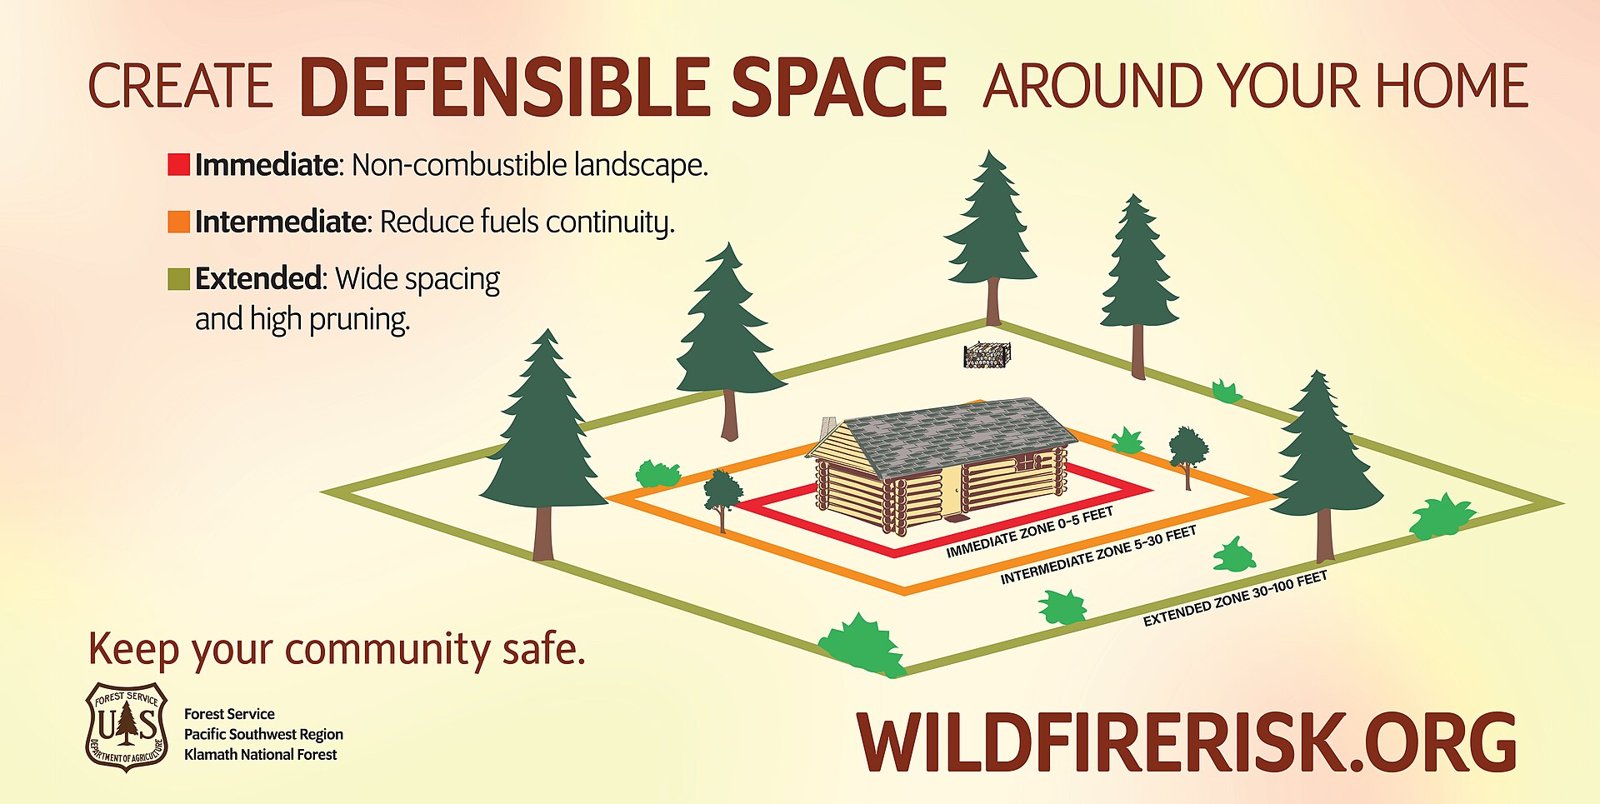
Defensible space zones | 0–5 ft, 5–30 ft, 30–100 ft | Colorado State Forest Service |
Jeffco Wildfire Resiliency Code | Approved Mar 10, 2026; applies to permits applied for on/after July 1, 2026, in the unincorporated WUI | Jefferson County |
The Colorado FAIR Plan: the backstop, not the plan
The Colorado FAIR Plan is the state's insurer of last resort, created by HB23-1288. Per the FAIR Plan and state law:
- You apply only through a licensed insurance agent, with proof that three insurers declined the property.
- Homeowner coverage is capped at $750,000 for property and contents combined, on an actual cash value basis, not replacement cost.
- The Division of Real Estate describes it as having limited covered perils and higher premiums, and properties are still inspected.
Because of those limits, people who end up on the FAIR Plan often ask their agent about pairing it with other coverage. That's a question for your agent, not me.
What a Jeffco foothills buyer should do
- Get quotes early. I'd start once you're serious about a home, and before your inspection objection deadline. Ask your lender and agent how timing fits your contract.
- Ask for the wildfire risk notice. The DOI says to contact your agent or insurer right away if you don't receive it.
- Ask the seller what mitigation is documented. Receipts, photos, a defensible space assessment, or a designation like IBHS Wildfire Prepared Home are what the law lets you use on appeal.
- Walk the home ignition zone. The Colorado State Forest Service splits it into Zone 1 (0–5 ft), Zone 2 (5–30 ft) and Zone 3 (30–100 ft), and says Zone 1 needs the most vigilant work.
- Shop around. The DOI's own advice is to compare insurers and coverage, not just price.
What an owner can do before renewal
- Read the wildfire risk notice that comes with your renewal.
- Check your insurer's website for its mitigation discounts and appeal steps.
- Keep a simple folder of mitigation work: dates, photos, invoices.
- If you think your score is wrong, appeal with that evidence. If the insurer doesn't follow the timelines, the DOI takes complaints at 303-894-7490 or doi.colorado.gov.
Remodeling in the foothills: Jeffco's new code
If you're buying a fixer, this matters. Jefferson County's Wildfire Resiliency Code was approved March 10, 2026 and applies to permits applied for on or after July 1, 2026, in the unincorporated WUI. The county says it isn't retroactive. It covers new buildings and exterior work like additions, re-roofing, re-siding and deck replacement, with requirements for roofing, gutters, vents, siding, windows and defensible space. Ask Jeffco Planning and Zoning whether a property falls in the WUI overlay, and plan the budget around it. I go deeper on buying and renovating in my buy + renovate guide.
Selling? Documented mitigation is worth having on hand for buyers. My remodel-before-selling guide covers which updates to think about first.
FAQs
Does HB25-1182 lower my premium?
Not automatically. It requires transparency, a way to appeal, and recognition of qualified mitigation. Whether that changes your premium depends on your insurer. Ask your carrier.
Does the law apply to every insurer?
No. The DOI says it applies to admitted insurers and the Colorado FAIR Plan, not to non-admitted or surplus lines insurers.
How fast do I get my wildfire risk score when I apply?
Within 15 days of a completed application, per the DOI. Existing policyholders get it with their renewal or nonrenewal notice.
How do I appeal my wildfire risk score?
Submit an appeal to your insurer with evidence of property- or community-level mitigation. The insurer must acknowledge it within 10 calendar days and decide within 30.
Who qualifies for the Colorado FAIR Plan?
Owners who can show three insurers declined the property. You apply through a licensed insurance agent. Homeowner coverage tops out at $750,000 for property and contents, at actual cash value.
What are the defensible space zones?
The Colorado State Forest Service uses three: 0–5 feet, 5–30 feet, and 30–100 feet from the home.
Does Jeffco's Wildfire Resiliency Code apply to my existing house?
Not retroactively. It applies to new construction and exterior alterations permitted on or after July 1, 2026, in unincorporated Jeffco's WUI.
Let's talk
If you're weighing a foothills home and want to know what to look for before you write an offer, I'm happy to walk through it with you. Reach out to me here and we'll set up a time.
Braden Wahr, The Apollo Group. This post is general information, not insurance or legal advice. Ask your carrier or licensed insurance agent about your policy.